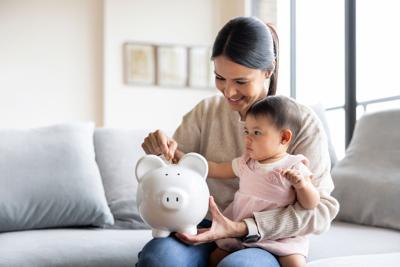

Happy Latin American mother saving money for her baby's future in a piggy bank - family concepts
Despite widespread financial stress, 61% of surveyed parents are currently saving for their children's future education costs. That number might surprise you -- not because saving for college is unusual, but because of the context surrounding it. These are the same parents who report going into debt for child-related expenses, losing sleep over monthly budgets, and in some cases, deciding not to have more children because they simply can't afford it. And yet, more than six in ten are setting money aside for a cost that may still be a decade away.
That kind of forward-thinking under financial pressure says something meaningful about how today's parents approach money. It's not that the stress isn't real -- it clearly is. It's that many families have found ways to hold two financial realities at once: managing the weight of today's debt while building toward tomorrow's goals.
The 61% Who Are Still Planning Ahead
People are also reading…
The financial picture for American parents is genuinely difficult. According to Rocket Mortgage's parenting cost report, 67% of parents say raising children is more expensive than they expected, with 38% describing costs as "much more" than anticipated. Nearly a quarter saw their monthly spending jump by $1,000 or more after having children. Fifty-eight percent have taken on credit card or loan debt specifically for child-related expenses, and 46% say child-related finances cause them stress always or usually.
Those are not abstract numbers. They represent real households making difficult choices every month.
So what explains the 61% who are still saving for education? Part of it may be prioritization -- a deliberate decision to treat college savings as non-negotiable, even when other financial pressures mount. Part of it may also be behavior design: Parents who automate contributions don't have to re-decide every month whether they can afford to save. The money moves before the temptation to redirect it elsewhere.
Whatever the explanation, the data suggests that saving for college and carrying child-related debt are not mutually exclusive. Many families are doing both, and understanding how requires a closer look at the strategies that make that possible.
How Families Balance Current Debt with Future Goals
The tension between paying down debt and building savings is not unique to parents, but the child-specific costs involved create particular pressure points. Childcare is among the most significant. The survey found that 54% of parents currently pay for childcare, and of those, 32% spend between 20% and 29% of their household income on it. Food and household goods represent the top monthly cost category at 38%, followed by childcare at 29%.
These expenses leave limited room for additional financial goals. But financial planners generally advise against treating debt payoff and savings as an either/or decision, and the survey data reflects that approach in practice.
One reason families are able to hold both is the structure of certain savings vehicles. A 529 college savings plan, for example, allows contributions of any size on any schedule. There is no monthly minimum. A parent carrying credit card debt can contribute $25 a month to a 529 while aggressively paying down a balance -- and over a 15-year period, that $25 a month, invested in a moderate-growth fund, can still add up to a meaningful sum. According to the College Board, the average published tuition and fees at a four-year public institution have increased significantly over the past decade, making early contributions -- even small ones -- worth more than contributions made closer to enrollment.
The key insight here is that time in the market matters more than the size of individual contributions, particularly when starting early. A family that opens a 529 when a child is born and contributes modestly for 18 years will almost always outperform a family that waits until the child is 12 and tries to catch up.
Practical Approaches to Education Savings Under Financial Pressure
For families trying to find the balance, a few approaches tend to work better than others.
Start with automation. The single most effective savings habit is removing the decision from the equation entirely. Setting up an automatic monthly transfer to a 529 -- even a small one -- means the contribution happens regardless of what else is competing for attention that month. The Investment Company Institute reports that 529 plan assets have grown steadily as more families adopt these accounts, in part because the accounts are easy to open and flexible to manage.
Match your savings rate to your debt type. High-interest credit card debt typically warrants aggressive repayment before any savings goal beyond a basic emergency fund. But lower-interest debt -- such as a personal loan or installment plan -- can reasonably coexist with ongoing savings contributions. The math works differently depending on interest rates, and running the numbers for your specific situation changes the decision significantly.
Set expectations that reflect reality. Most families will not fully fund a four-year college education through savings alone. Scholarships, work-study programs, and financial aid are part of the picture for most students. A college savings account doesn't need to cover the entire cost to be worth having -- even a partial contribution reduces future loan burden.
Revisit the plan annually. Financial circumstances shift. A parent who was stretched thin during the childcare years may have significantly more capacity once those costs drop. Building in a regular review means the savings rate can increase as room opens up in the budget.
What the Numbers Suggest About Parental Financial Priorities
The same survey that documents financial pressure also shows that 41% of parents cite the desire for homeownership stability after having children, and 43% say they need more space. These are strong, achievable aspirations — and the families pursuing them are doing so alongside education savings, not instead of it.
The 61% saving for education is a signal of that determination. What that figure reflects is a core parental instinct — the willingness to plan forward under real pressure, holding multiple goals at once. For many families, the goal isn't to resolve every financial challenge before acting. The goal is to build toward homeownership and education savings in parallel, adjusting the pace as the picture evolves. That kind of long-range thinking is exactly what makes both possible.